
The Canadian government has introduced a significant tax reform during the Canada Investment Summit, aiming to boost business investments in various sectors. The newly announced productivity mega-deduction will enable companies to deduct the full cost of new investments in areas such as machinery, equipment, clean energy, and zero-emission vehicles.
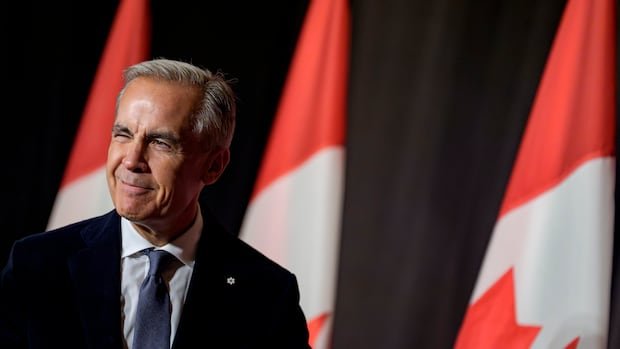
During the summit, Prime Minister Mark Carney expressed the government’s objective to position Canada as the most appealing destination for investments among the G7 nations. This initiative builds upon the productivity super-deduction introduced in the previous year’s budget, which initially covered a limited range of investments like equipment, machinery, and technology. With the expansion of the program, approximately two-thirds of assets will now qualify for the deduction.
Previously, Canadian businesses could recover costs over the project’s lifespan. However, the new program allows for immediate reimbursement, potentially encouraging investors to allocate more funds to new ventures. According to Randall Bartlett, Desjardins’ deputy chief economist, the aim is to incentivize companies to invest promptly and substantially, enhancing Canada’s competitive edge in terms of taxes compared to other countries.
The government estimates that the tax change will reduce Canada’s marginal effective tax rate from 13% to 6.4%, making it the lowest among G7 nations. This adjustment could prove crucial amid trade uncertainties, as it might persuade companies to retain operations in Canada and proceed with postponed investments.
While the tax reform is projected to cost around $36 billion over five years, Bartlett noted that the current revenue influx from high oil prices should mitigate immediate financial concerns. However, sustaining such expenditure in the long term will necessitate careful fiscal planning by the government.